Pre-Approval vs. Final Mortgage Approval: What Every First-Time Buyer in Saskatoon Needs to Know
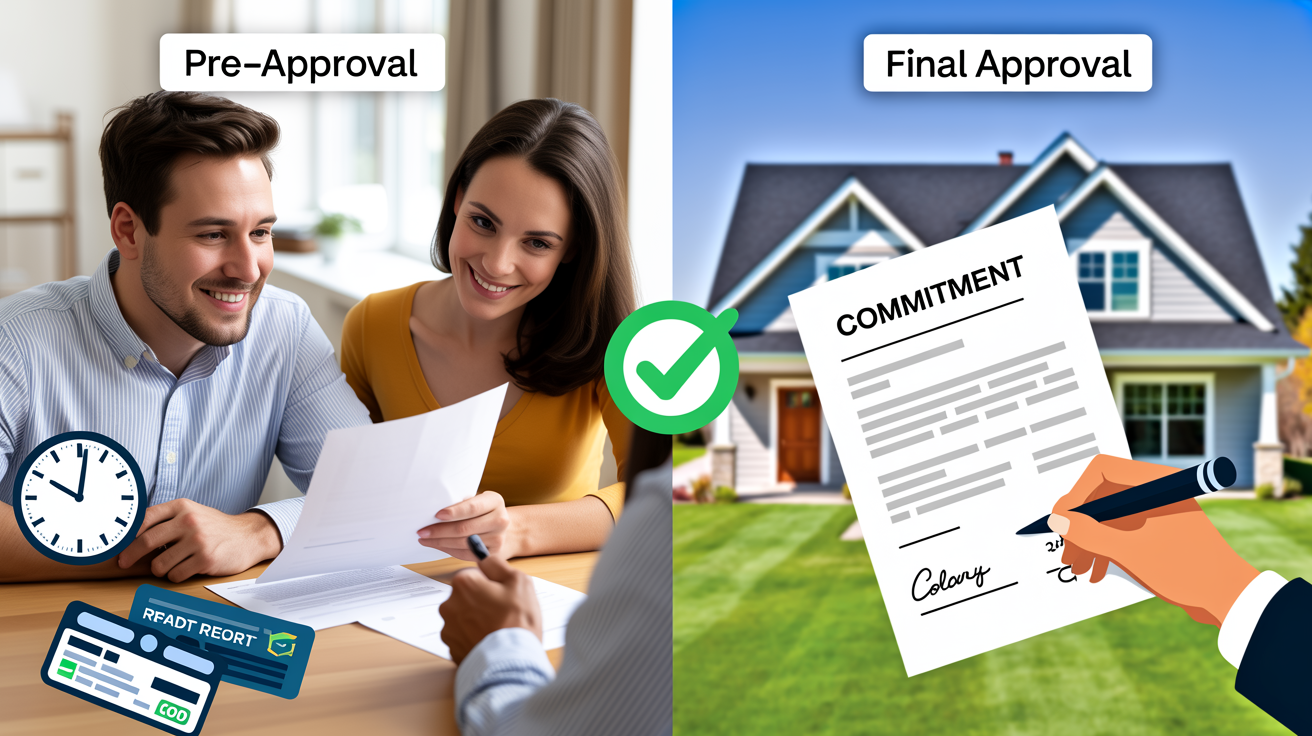
What's the difference between mortgage pre-approval and final approval in Saskatoon? A pre-approval estimates what you can borrow and usually holds a rate for 60 to 120 days, but it isn't a guarantee. Final approval comes after you have an accepted offer, once the lender verifies your documents and appraises the home. Always keep a financing condition in your offer.
Updated November 2026 by Clayton McNally & Jessica Hamel, REALTORS®, RE/MAX Saskatoon
What's the Difference Between Pre-Approval and Final Approval?
If you're a first-time homebuyer in Saskatoon, few things are more exciting — or more confusing — than navigating the mortgage process. You've probably heard the terms "pre-approval" and "final approval" used almost interchangeably, but they are not the same thing, and misunderstanding the difference could put your dream home at serious risk. As REALTORS® who work with buyers across Saskatoon every day, we want to break down exactly what each stage means, what's required, and how to protect yourself from costly surprises along the way. (For the full journey from pre-approval to possession, see our free Saskatoon Home Buyer's Guide.)
Watch: Mortgage Pre-Approval vs. Final Approval
Is Pre-Qualified the Same as Pre-Approved?
No. A pre-qualification is usually based on rough numbers you give your mortgage broker. A pre-approval means your broker has actually reviewed your documents. That difference matters most when the clock is ticking on your conditions.
A real example from our files: First-time buyers are often surprised by how much information their mortgage broker needs before financing can be approved, which is a big reason to get pre-approved ahead of time so you aren't overwhelmed during the time crunch before conditions come off. Recently, a deal collapsed for one of our buyers because they had only been pre-qualified, not pre-approved. They had given their broker rough estimates instead of their actual documents, and it caught up with them during the condition period.
What Happens During a Mortgage Pre-Approval?
Think of a mortgage pre-approval as your official permission slip to start house hunting. Before you fall in love with a home on Waskimo Crescent or put in an offer on a character bungalow in Nutana, a pre-approval gives you a realistic spending ceiling — the maximum mortgage amount a lender is likely to provide based on your current financial standing. You can get a ballpark first with our Saskatoon mortgage calculator, then see what that budget buys.
Here's what the pre-approval process typically involves:
- A review of your pay stubs, tax returns, and credit report
- A preliminary credit check to assess your creditworthiness
- An estimate of your maximum borrowing amount and an associated interest rate
- A rate hold of 60 to 120 days, which protects you from interest rate increases while you search
One critical thing to understand: a pre-approval is based largely on unverified financial claims and a cursory document review — not a full deep dive into your finances. It is a conditional estimate, not a legal guarantee. The lender has not yet committed to providing you with the funds. This is why it's sometimes called a "soft" approval.
It's also worth noting that Canadian buyers must pass the mortgage stress test, which means qualifying at the higher of 5.25% or your contract rate plus 2%. This applies to both insured and uninsured mortgages, and it's factored into your pre-approval amount. If your financial situation changes — a new car loan, a job change, or a significant purchase — between pre-approval and closing, your pre-approved rate and amount are not guaranteed.
What Happens During Final Mortgage Approval?
Final mortgage approval is a different animal entirely. This stage is only triggered once you have a signed purchase agreement on a specific property. At this point, your lender shifts into full verification mode.
Here's what happens during final approval:
- Full income and employment verification — the lender thoroughly reviews your tax returns, pay stubs, and employment history
- A professional property appraisal is ordered to confirm that the purchase price does not exceed the property's fair market value
- A complete review of your credit history and any changes to your financial profile since pre-approval
- If everything checks out, the lender issues a formal commitment letter — a binding legal agreement to provide the mortgage funds
That property appraisal is an important detail first-time buyers often overlook. In Saskatchewan, appraisals typically cost between $300 and $500, and this cost is paid by the buyer. The lender orders it, but you foot the bill. Budget for it accordingly.
Additionally, if your down payment is less than 20% of the purchase price, CMHC mortgage insurance is required by Canadian law. This insurance protects the lender — not you — but the premium is added to your mortgage, so it's important to factor it into your overall costs. Our guide to deposit vs. down payment explains how much cash you'll need and when.
Should You Include a Financing Condition in Your Offer?
Yes. Here is advice we give every buyer we work with in Saskatoon: always include a "Subject to Financing" clause in your purchase offer — even if you have a pre-approval in hand. Because final approval requires both a full document review and a property appraisal, there are scenarios where financing can fall through even after a pre-approval. This clause gives you a legal exit if your financing doesn't come through, protecting your deposit and your peace of mind. (In a competitive situation, our multiple-offer tips explain how to keep your offer strong without giving up key protections.)
What First-Time Buyer Programs Are Available in Saskatchewan?
As a first-time buyer in Saskatoon, you may be eligible for programs that can ease the financial burden:
- The federal First-Time Home Buyers' Tax Credit, which provides up to $1,500 in tax relief
- The Saskatchewan First-Time Homebuyers' Tax Credit, an additional provincial credit to help offset closing costs
These programs won't replace a solid mortgage strategy, but they're meaningful savings that you shouldn't leave on the table. See our 2026 guide to Saskatchewan home buyer incentive programs for the full list, including the FHSA and RRSP Home Buyers' Plan.
What Should You Avoid Between Pre-Approval and Final Approval?
This is where many first-time buyers unknowingly derail their own mortgage. Between the time you receive your pre-approval and the day your final approval is issued, avoid making any major financial changes. That means:
- No new car loans or large financing agreements
- No significant credit card purchases or new lines of credit
- No job changes or gaps in employment
Lenders will re-verify your financial situation before issuing the commitment letter. Any change that increases your debt load or reduces your income could result in a reduced mortgage amount — or a declined application altogether. For more pitfalls to avoid, read 5 costly mistakes first-time buyers in Saskatoon must avoid, and our top 5 tips for first-time buyers in Saskatoon.
Ready to Start Your Homebuying Journey in Saskatoon?
Understanding the mortgage process is just one piece of the puzzle. Having Clayton and Jessica, your trusted REALTORS®, in your corner — REALTORS® who know Saskatoon's neighbourhoods, market conditions, and how to structure a competitive offer — makes all the difference. Our First-Time Buyers page brings together starter-home listings, closing costs and current programs.
If you have questions about the homebuying process, want guidance on what to expect, or are ready to book a showing, talk to Clayton and Jessica today. Clayton and Jessica bring local expertise and a genuine commitment to helping first-time buyers navigate every step with confidence. In the meantime, browse homes for sale in Saskatoon or get in touch here.
Call or text Jessica at 306.241.6029 or Clayton at 306.341.4401 — your Saskatoon real estate questions deserve real answers.